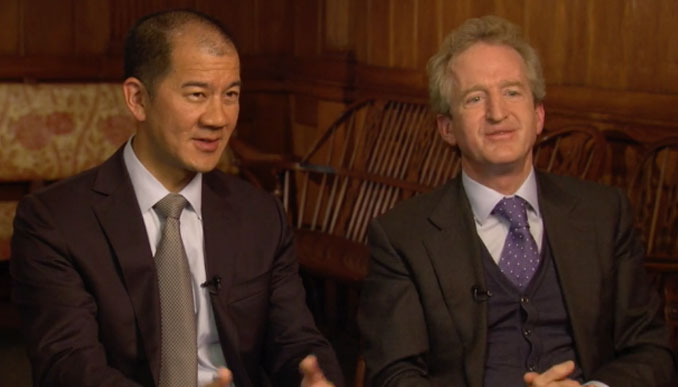
Everybody loves a rising market, but what to make of the fact that they are concentrated in a few names at the top, with expensive valuations?
Transcript
Danton Goei:
If you just look at the top 5, for example, today, which is the red bar versus 2016, so a decade ago at the blue bar, you can just see how much the market concentration has increased. And if you look at the top 10 are almost 40% of the index, so it's pretty amazing. So yeah, it has become extremely, extremely concentrated at the top especially. And then you can see that here where you can see the weightings here of the top 10 holdings in the index.
And you can see that one, it's dominated by tech. On the right side, you see there the names one after another. They're all technology except for the very last one where JP Morgan, but all the rest are all technology names. And you can also see that those weightings at the very top are much larger than they used to be for the top weighting in the index a decade ago, more than double sometimes, or triple even, the weightings of the top four or five in the previous decade. So energy, financials, telecoms have all become tiny parts of the index, and today technology is about half of the entire market. So really not diversified in a lot of concentration, both in names and sector. And then if you think the risk profile in terms of the valuation, think about what used to be the largest name in the index a decade ago, Apple with a PE of 10 and a price of sales of two and a half times and generating a lot of cash.
Today, it's, as we know, Nvidia, and the PE and the price of sales are dramatically higher, 28 times and 18 and a half with an over $5 trillion market capitalization and lower free cash generation as well. So the risk profile in terms of valuation has also dramatically increased.
Chris Davis:
I guess I would just highlight one other thing. Again, saying we're open-minded, but it is amazing. Apple didn't have its largest customers actively competing against it, and that they, in a sense, built an ecosystem. Nvidia's working hard to do that, but it is given our long history with Google and with Amazon, we've watched the development of the chip efforts there. I just think the margin sustaining at NVIDIA is a very bold assumption, especially when that ecosystem could change in that way.
Danton Goei:
I mean, that's a good point. And like you said, we're open-minded. At the right price, we would be open to owning NVIDIA, but the assumption that there are 66% operating margins today are going to sustain for many years in the future, and also you can have a huge sales growth figure as well. It just seems that there's a lot of risk to that.
More Videos
Separating Hype from Opportunity – Investment Implications of AI (4:44)
“Value Creators and Price Takers” - Investing in Healthcare Today (4:42)